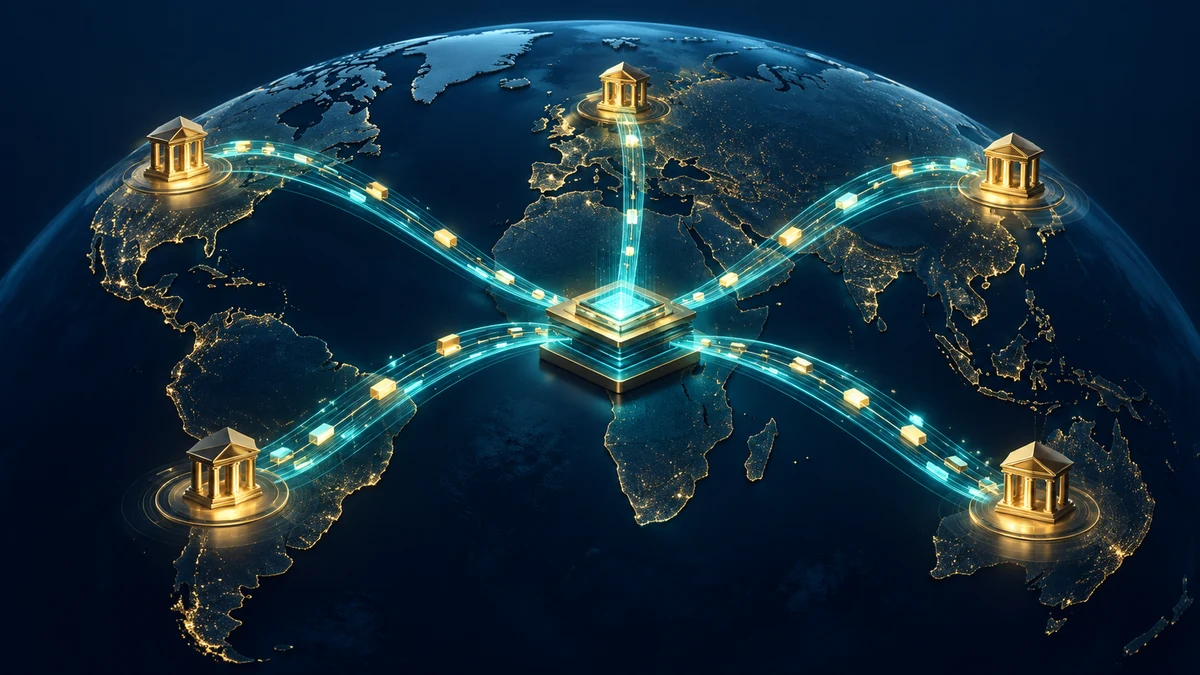
Swift's September 28 Sibos update reports that most of its 17 first-mover banks have used the blockchain ledger for around-the-clock payments. The reported transactions span EUR, GBP, HKD, SGD and USD. Swift: cross-border payments and tokenised value at Sibos 2026
Follow the evidence
Trace how the event could reach markets, then inspect a competing explanation.
Compare explanations
Switch lenses to see what each account explains—and what remains uncertain.
In its subsequent MVP update, Swift described an EVM-compatible architecture based on Hyperledger Besu. The proposed operational division leaves banks in control of their keys, assets, funding and settlement arrangements, while Swift operates the ledger and coordinates workflows and funding commitments. The update also identifies tokenised deposits as the initial representation of value. Swift: shared ledger moves to MVP implementation WFN analysis: this design makes settlement arrangements as important as the ledger technology. A token moving through a system does not by itself explain which institution owes the money, when an obligation is discharged or how a recipient converts the balance into funds usable elsewhere. Those questions belong in the service documentation. For a broker or payment provider, the relevant comparison is the end-to-end workflow: participating banks, supported corridors, opening hours, reconciliation and total cost. A technical connection is only one component. The Sibos milestone can justify further investigation without establishing a better commercial outcome for every business.
In its subsequent MVP update, Swift described an EVM-compatible architecture based on Hyperledger Besu. The proposed operational division leaves banks in control of their keys, assets, funding and settlement arrangements, while Swift operates the ledger and coordinates workflows and funding commitments. The update also identifies tokenised deposits as the initial representation of value. Swift: shared ledger moves to MVP implementation WFN analysis: this design makes settlement arrangements as important as the ledger technology. A token moving through a system does not by itself explain which institution owes the money, when an obligation is discharged or how a recipient converts the balance into funds usable elsewhere. Those questions belong in the service documentation. For a broker or payment provider, the relevant comparison is the end-to-end workflow: participating banks, supported corridors, opening hours, reconciliation and total cost. A technical connection is only one component. The Sibos milestone can justify further investigation without establishing a better commercial outcome for every business.
The September update distinguishes the ledger from Swift's work improving existing payment rails. Swift's earlier strategy also explicitly pursued both established fiat infrastructure and digital rails. Presenting the ledger as a replacement for all conventional payments would go beyond the reported programme. Swift: shared-ledger announcement in September 2025 The next evidence should identify live customer services, eligibility, settlement terms and actual fees for a named corridor. Performance claims should state the transaction stage being measured. Swift's account of early use supports a deployment milestone; it does not establish a market price effect for ether, a public-chain transaction volume or a guarantee of instant receipt by every beneficiary.
A reported deployment milestone, with a defined participant group
Swift describes tokenised value moving between Africa, Asia, Australia, Europe, North America and South America. Reported use cases include interbank settlement, corporate treasury and interbank funding. These are Swift's statements about participating institutions; the announcement does not establish universal customer access or publish a complete independent transaction dataset. Swift: cross-border payments and tokenised value at Sibos 2026
The September 2025 announcement had outlined a shared ledger developed with more than 30 financial institutions, beginning with a conceptual prototype involving Consensys. Its first intended use case was real-time cross-border payments available at all hours. That earlier statement was a development plan and should not be retrospectively described as a completed 2025 global rollout. Swift: shared-ledger announcement in September 2025
The ledger coordinates bank workflows as well as token transfers
In its subsequent MVP update, Swift described an EVM-compatible architecture based on Hyperledger Besu. The proposed operational division leaves banks in control of their keys, assets, funding and settlement arrangements, while Swift operates the ledger and coordinates workflows and funding commitments. The update also identifies tokenised deposits as the initial representation of value. Swift: shared ledger moves to MVP implementation
WFN analysis: this design makes settlement arrangements as important as the ledger technology. A token moving through a system does not by itself explain which institution owes the money, when an obligation is discharged or how a recipient converts the balance into funds usable elsewhere. Those questions belong in the service documentation.
For a broker or payment provider, the relevant comparison is the end-to-end workflow: participating banks, supported corridors, opening hours, reconciliation and total cost. A technical connection is only one component. The Sibos milestone can justify further investigation without establishing a better commercial outcome for every business.
Where does the reported service become available to customers?
The September update distinguishes the ledger from Swift's work improving existing payment rails. Swift's earlier strategy also explicitly pursued both established fiat infrastructure and digital rails. Presenting the ledger as a replacement for all conventional payments would go beyond the reported programme. Swift: shared-ledger announcement in September 2025
The next evidence should identify live customer services, eligibility, settlement terms and actual fees for a named corridor. Performance claims should state the transaction stage being measured. Swift's account of early use supports a deployment milestone; it does not establish a market price effect for ether, a public-chain transaction volume or a guarantee of instant receipt by every beneficiary.